

Personal
Business
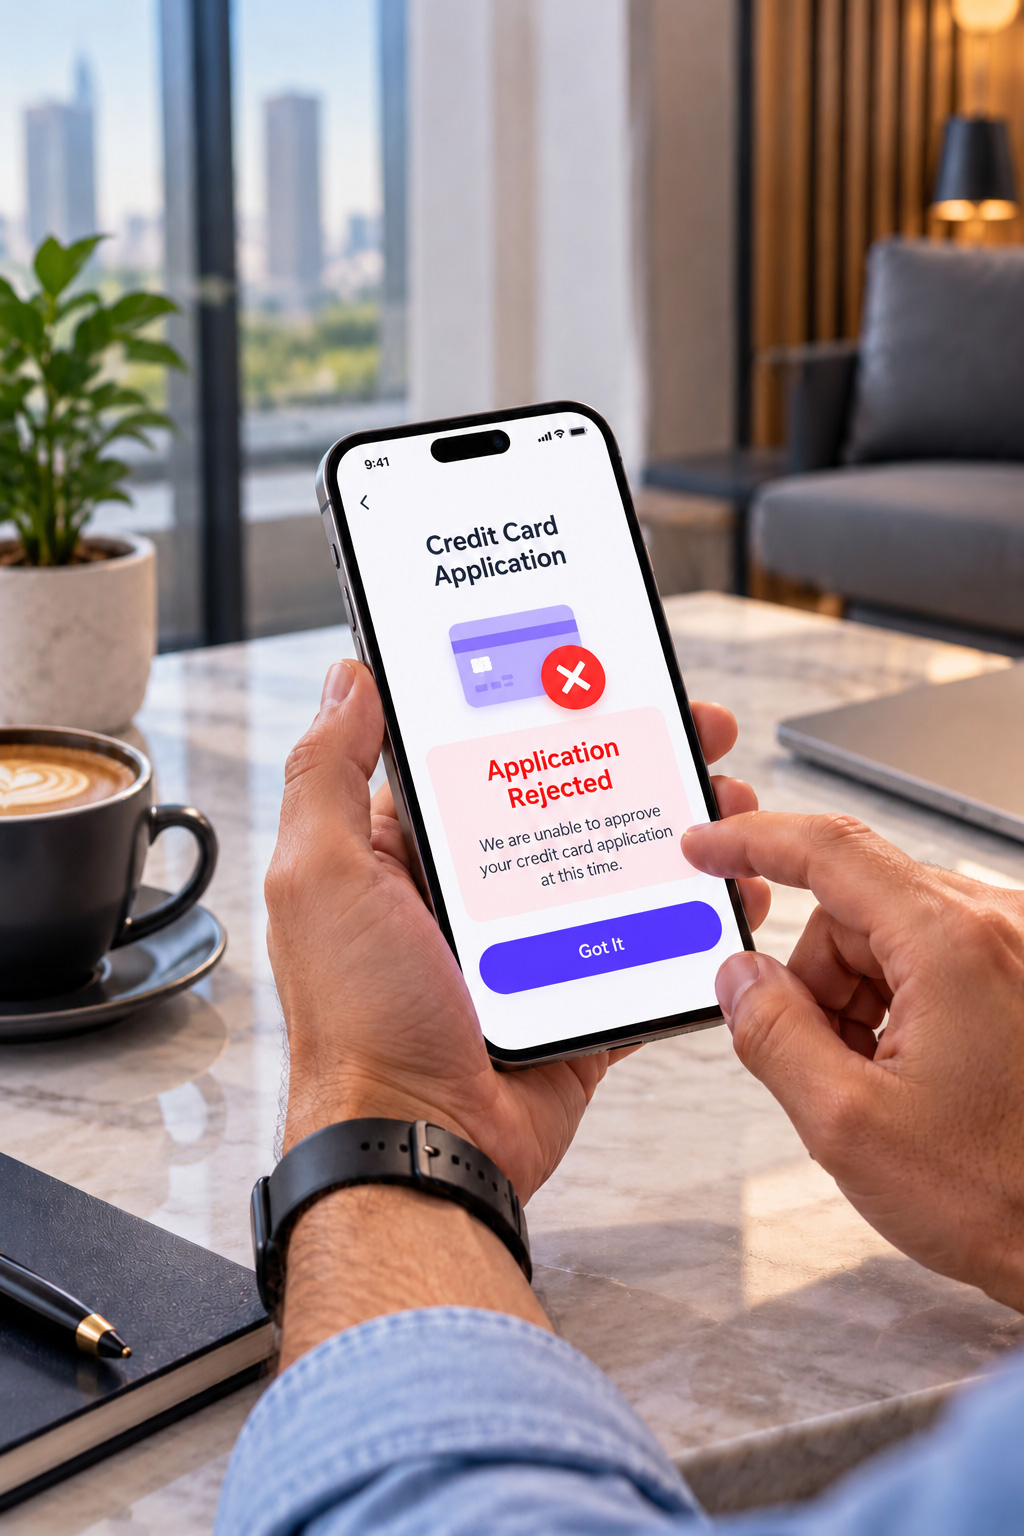
Having your credit card application rejected can be frustrating, especially if you believe you meet the eligibility requirements. But meeting the minimum salary requirement is only one part of the approval process.
In the UAE, credit card providers consider several factors when reviewing applications, including income, credit history, existing financial commitments and the ability to manage additional repayments.
If your application has been declined, understanding what may have affected the decision can help you decide what to do next.
This guide explains why credit card applications may be rejected in the UAE, how Deem assesses eligibility and what you should check before applying again.
Why Do Credit Card Applications Get Rejected in the UAE?
A credit card application may be declined for several reasons. These can include:
These are possible factors, not a definitive explanation of any individual rejection. The actual reason depends on the provider’s assessment of your application.
How Does Deem Assess Credit Card Applications?
When you apply for a Deem Credit Card, your application is assessed against the applicable eligibility requirements and Deem’s credit and affordability criteria.
The assessment considers several aspects of your financial position.
1.Your Income and Card Eligibility
Different Deem Credit Cards have different minimum monthly income requirements. The currently published requirements are:
Meeting the minimum income requirement means you satisfy that particular criterion. It does not guarantee approval.
For example, an applicant earning AED 10,000 per month meets the published minimum income requirement for a Deem Platinum Credit Card. However, Deem must still assess the applicant’s credit history, financial commitments and affordability before making a decision.
Your credit history provides information about how you have managed existing financial obligations.
Information from Etihad Credit Bureau, also known as AECB, can help lenders review your borrowing and repayment history.
A credit assessment may consider whether you have existing loans or credit cards, your outstanding obligations and your record of making payments.
A strong credit score can be positive, but it does not guarantee approval. Similarly, the credit score alone does not explain every application decision.
Deem also considers how additional credit would fit alongside your existing financial obligations.
This includes relevant commitments such as personal loans, car loans, home finance and credit card facilities.
Your Debt Burden Ratio (DBR) is one measure used to assess these commitments. It compares your assessed monthly debt repayments with your eligible monthly income.
Under the Central Bank of the UAE’s lending regulations, total assessed debt repayments must generally remain within 50% of gross salary and qualifying regular income, subject to applicable requirements.
However, having a DBR below this limit does not automatically mean an application will be approved.
Learn more in our guide to Debt Burden Ratio in the UAE.
Beyond meeting eligibility requirements, affordability is an important consideration.
This means assessing whether additional credit can be managed alongside existing repayments and other financial responsibilities.
The aim is to ensure that any credit facility offered is appropriate for your financial circumstances.
All Deem Credit Card applications remain subject to the applicable eligibility criteria, verification, credit assessment and approval.
What Should You Check After Your Credit Card Application Is Rejected?
Before submitting another application, review the following areas to understand what may need attention.
Start by checking the outcome communicated by the credit card provider.
An application may be declined, still under review or awaiting additional information. These are different outcomes, so confirm the status before taking further action.
Under the UAE’s Consumer Protection Standards, financial institutions are required to communicate the reason for rejection in writing, except where the reason relates to financial crime risks or where disclosure is prohibited by law.
Review the explanation provided and contact the card issuer if you need clarification.
Understanding the reason is more useful than immediately submitting another application.
Your credit report contains information about your existing credit facilities, financial obligations and repayment history.
You can obtain your report through Etihad Credit Bureau.
When reviewing it, check whether:
If you identify incorrect information, request a correction through Etihad Credit Bureau’s Data Correction service and provide the relevant supporting documents.
Remember that changes such as loan settlements or credit limit reductions may not appear immediately in your report. Accurate records of past missed payments may also remain visible.
Even if you pay your bills on time, your existing borrowing commitments can affect your eligibility for additional credit.
For example, you may have a personal loan, a car loan and several credit cards. The provider will need to consider your assessed commitments when reviewing whether you can manage another facility.
An important point to remember is that credit card limits may be considered even when the cards are not being used, depending on the assessment method.
Before applying again, review your current facilities and determine whether you need all your existing credit limits.
If you are considering reducing a limit or closing an account, confirm any outstanding balances, applicable charges and the effect of the change with your current provider.
Incorrect or incomplete information can delay the application process or affect the provider’s ability to complete its assessment.
Before applying, check that your:
For example, if your salary has recently changed, make sure the income you declare is supported by the documents you submit.
If you have changed employers, provide accurate employment information and any supporting documents requested.
Requirements may vary depending on the applicant and the card provider, so always confirm what is needed.
If one application is rejected, submitting several more applications immediately may not be the best next step.
Credit card applications can involve credit bureau enquiries, and multiple applications within a short period may affect your credit profile.
More importantly, applying to another provider without understanding the original rejection may mean that the same financial or eligibility concerns remain.
Instead, review the previous decision, check your financial information and consider whether anything relevant has changed.
Each provider makes its own assessment, so a declined application with one institution does not automatically mean another provider will reach the same decision.
When Should You Reapply for a Credit Card?
There is no single reapplication timeframe that applies to every credit card provider or every declined application in the UAE.
The appropriate next step depends on the reason your application was rejected and the requirements of the provider.
For example, if additional documents were required, you may need to submit updated information. If the concern relates to existing debt obligations, you may need to review your financial position before considering additional credit.
Before reapplying, ask yourself:
Do I understand why my previous application was declined?
Have I checked my credit report for inaccuracies?
Are my income details and supporting documents up to date?
Can I comfortably manage another credit card alongside my existing expenses and repayments?
Have I confirmed whether a new application is required and when I can submit it?
Addressing these questions can help you make a more informed decision. However, completing these steps does not guarantee a different application outcome.
Considering a Deem Credit Card? Start With the Right Information
If you are planning to apply for a Deem Credit Card, start by reviewing the available cards and their eligibility requirements.
Choose a card that matches your income, spending needs and ability to manage repayments.
Before applying, review the Credit Card Key Facts Statement to understand the applicable fees, finance charges, repayment obligations and important product conditions.
You can explore Deem Credit Cards online and review the available options.
For assistance with your application or information on the documents required, contact Deem Customer Care at 600 525550.
All applications are subject to Deem’s eligibility criteria, affordability and credit assessment, verification and approval.
Frequently Asked Questions
Why was my credit card application rejected even though I meet the minimum salary?
Meeting the minimum salary requirement does not guarantee credit card approval. Providers also consider your credit history, existing financial commitments, affordability and other applicable eligibility requirements. Review the reason communicated by your card provider to understand the outcome.
Can I get a Deem Credit Card if I already have other credit cards?
Having existing credit cards does not automatically mean your application will be rejected. Deem considers your existing financial commitments, credit history and ability to manage additional credit as part of its assessment. Approval is subject to the applicable eligibility and credit criteria.
Can my credit card application be rejected even with a good AECB score?
Yes. A credit score is only one part of an application assessment. Your income, existing repayment obligations, affordability and other eligibility requirements are also relevant. A good credit score does not guarantee approval.
Does a rejected credit card application affect my credit score?
A rejection is not the same as a missed payment. However, the application process may involve a credit bureau enquiry, which can influence your credit profile. The effect of an enquiry depends on the wider information in your credit record.
How long should I wait before applying for another credit card?
There is no universal waiting period. Check the requirements of the card provider and review the reason for your previous rejection before submitting another application. Waiting alone does not guarantee approval.
Can I apply for a Deem Credit Card after being rejected by another provider?
You can consider applying for a Deem Credit Card if you meet the applicable eligibility requirements. Deem will conduct its own credit and affordability assessment, and approval is not guaranteed. It is advisable to understand the reason for your earlier rejection before applying.


© All rights reserved 2026 Deem Finance LLC. Deem Finance LLC (Deem) is regulated by Central Bank of the UAE.